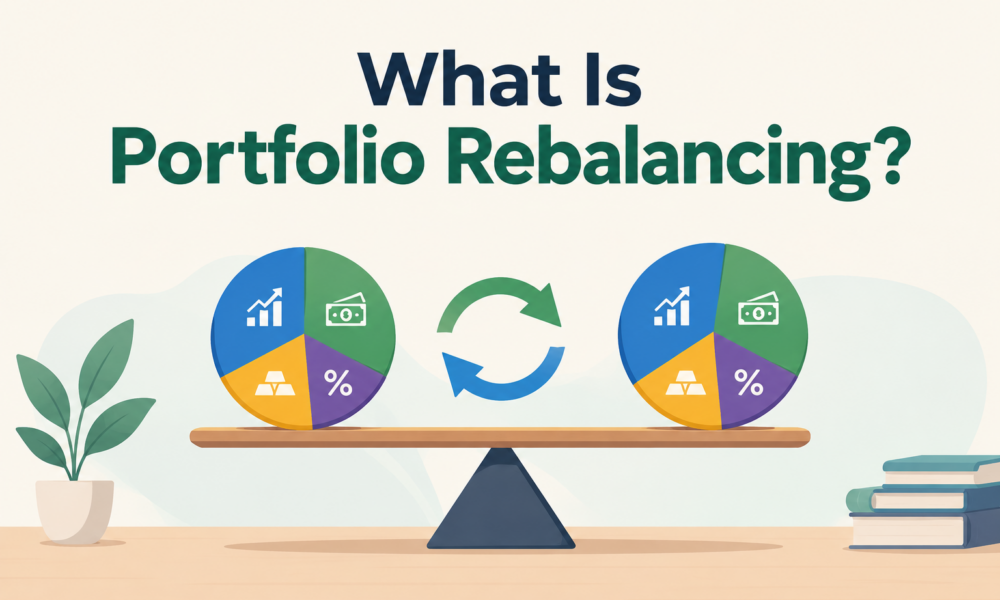
What Is Portfolio Rebalancing?
Say you started investing with a simple plan: 60% in equity mutual funds and 40% in debt funds. A year later, the stock market has had a great run, and your equity share has quietly grown to 72%....
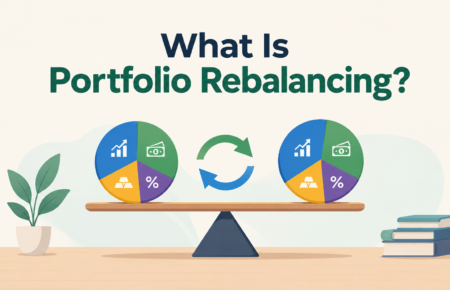
Say you started investing with a simple plan: 60% in equity mutual funds and 40% in debt funds. A year later, the stock market has had a great run, and your equity share has quietly grown to 72%. Your investment portfolio has changed, even though you didn’t alter anything. It no longer matches your original plan.
Table Of Content
A portfolio rebalancing strategy helps investors bring their investments back to their intended allocation.
That gap is exactly what portfolio rebalancing fixes. It means getting your investments back to your original plan. You do this by selling some of what has grown too large and adding to what has lagged.
Why Portfolio Rebalancing Matters
Your asset allocation is a statement about how much risk you can live with. If you chose 60:40, you were saying you’re comfortable with that level of ups and downs. When equity hits 72%, you take on more risk than planned. A market drop will sting more than you thought.
This slow shift has a name: portfolio drift. It happens quietly, which is why many people only notice it when a crash arrives.
The portfolio rebalancing benefits include keeping your risk aligned with your original investment plan.
So why rebalance portfolio holdings at all? It helps keep your portfolio’s risk aligned with your target allocation, encourages you to trim positions that have grown too large,and allows you to add to asset classes that have become underweight.
How Portfolio Rebalancing Works
Start with your target allocation, the split you set based on your goals, age, and comfort with risk. Then check where you stand today. If the gap is large, you fix it.
If you’re wondering how to rebalance your portfolio, start by comparing your current allocation with your target allocation.
Here’s a quick example. Say you have ₹10 lakh, split as ₹6 lakh in equity funds and ₹4 lakh in debt funds. After a rally, equity is worth ₹8.4 lakh and debt is ₹4.4 lakh, so the total is ₹12.8 lakh. Equity now makes up about 66%.
To get back to 60:40, you need ₹7.68 lakh in equity and ₹5.12 lakh in debt. That means moving roughly ₹72,000 from equity funds to debt funds. This simple example shows how to rebalance your portfolio when one asset class becomes overweight.
Common Rebalancing Strategies
There’s no single perfect rebalancing strategy. Most investors pick one of these:
The right portfolio rebalancing strategy depends on how often you want to review your investments.
- Calendar-based: Review once or twice a year, say every April, and adjust no matter what the market does.
- Threshold-based:Only act if an asset class moves a set amount away from its target, such as 5 percentage points.
- Cash-flow based: Use fresh SIPs, bonuses, or maturity money to fill the gap as in the example above.
- Hybrid: Check yearly, but rebalance only if the threshold is crossed.
Things to Keep in Mind
When to rebalance portfolio holdings is a common question. The honest answer is: not too often. For many long-term investors, reviewing the portfolio once a year can be a practical approach, although the right frequency depends on the investor’s strategy and circumstances.
Taxes and other costs also matter. Taxes and other costs also matter. The tax treatment of mutual fund gains can depend on the type of fund, how long you have held the units, and the applicable tax rules. Check the latest tax rules before redeeming units. Exit loads may also apply if you sell within a specified period. Always check the latest tax rules and fund terms before making a move.
Your target allocation isn’t permanent either. A job change, a new baby, a major financial goal, or getting closer to retirement can all be reasons to review your allocation. Your investment mix should reflect your current goals, time horizon, and comfort with risk.
Emotions are another hurdle. Portfolio rebalancing often means cutting back on investments that have performed well and adding to those that have lagged. That can feel strange, especially when everyone else is talking about their recent returns. But the goal is to stay aligned with your plan rather than react to short-term market movements. Discipline is the whole point.